

Doctors, you work too hard to lose money on a tax strategy that sounds almost too good to be true.
What if you owe the federal government $300,000 in taxes?
Then someone tells you:
“I can reduce your tax bill by $200,000.”
The cost?
Only $100,000.
Would you do it?
Who wouldn’t—if it were legitimate?
Spend $100,000. Save $200,000 in taxes.
No-brainer.
And that is essentially the pitch behind a tax strategy being marketed to high-income taxpayers.
Let me show you how it supposedly works.
Here’s the Pitch
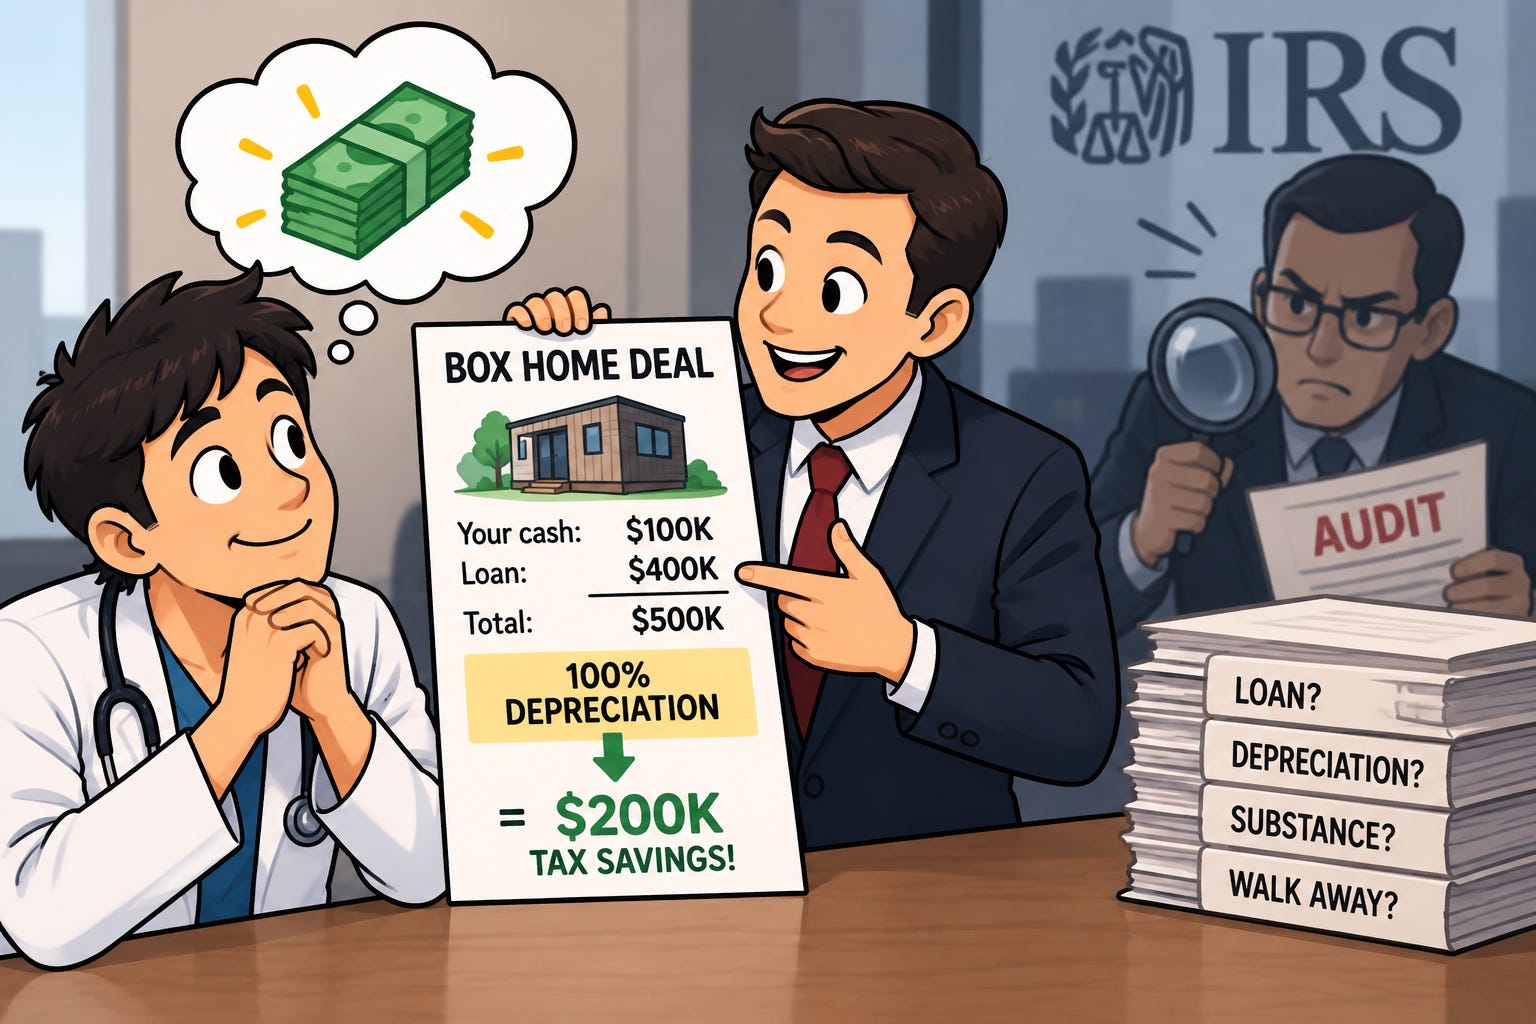
You buy what I’ll call a “box home” to operate as a short-term rental.
The numbers look something like this:
Your cash: $100,000
Loan: $400,000
Total: $500,000
The promoter claims the box home qualifies for 100% bonus depreciation.
So even though you put in only $100,000 of your own money, you potentially claim a:
$500,000 deduction.
At a hypothetical 40% tax rate, that’s potentially:
$200,000 in tax savings.
You spent $100,000.
You potentially saved $200,000.
Pretty awesome.
If it works.
But Wait. It Gets Better.
Here’s the part that gets my attention.
You’re told that the following year, you may be able to:
Walk away from the $400,000 loan.
So you put in $100,000, potentially save $200,000 in taxes...and then walk away?
Is there really a free “steak-and-lobster” lunch?
Because somebody has to pay for it.
Is That $400,000 Really a Loan?
This is the first question I’d ask.
That $400,000 loan is important because it’s helping create the huge $500,000 deduction.
Without it, you didn’t put $500,000 into the deal.
You put in $100,000.
So ask yourself:
If I can walk away from a $400,000 loan without meaningful consequences, was I really $400,000 in debt?
I’d want to know:
Who is lending the money?
Does the lender actually expect to get paid back?
What happens if I don’t repay it?
And if “you can just walk away” is part of the sales pitch...
is this really a loan?
Walking Away Doesn’t Make the Tax Problem Disappear
Here’s where the strategy gets really interesting.
Either the $400,000 loan is real, or it isn’t.
If it is a real loan, and you used the entire $500,000 to generate a depreciation deduction, your tax basis may now be $0.
Then the next year, you walk away from the property—and the $400,000 loan goes with it.
For tax purposes, that doesn’t necessarily mean the $400,000 simply disappears.
You could end up recognizing $400,000 of taxable income or gain when you exit the deal.
Think about what just happened:
Year 1: You get a huge deduction.
Year 2: Much of that tax benefit may come right back as taxable income.
So the promise that you can “just walk away” doesn’t mean you walk away tax-free.
But there’s another possibility.
What if the $400,000 isn’t really a loan?
Then I have an even simpler question:
Why should you be allowed to take a deduction based on $400,000 of debt that was never real in the first place?
You put in $100,000 of your own money.
If the other $400,000 isn’t bona fide debt, how did you suddenly get a $500,000 basis and a $500,000 deduction?
That’s the problem.
If the loan is real, walking away may create a big tax bill.
If the loan isn’t real, the big deduction may never have been legitimate in the first place.
Either way, “you can just walk away next year” isn’t nearly as simple as it sounds.
And That’s Just the Loan
There are other questions too.
Is the box home really eligible for 100% bonus depreciation?
Is this actually a legitimate short-term rental business?
Did you participate enough in the activity to use the loss against your physician income?
These aren’t minor details.
They’re what determine whether the strategy actually works.
Why Physicians Are Attractive Targets
Physicians work incredibly hard.
We make good money.
We pay a lot in taxes.
And most of us learned almost nothing about taxes during our medical training.
I certainly didn’t.
We’re also busy.
So when someone says:
“Our attorneys reviewed it.”
“Other doctors are doing it.”
“Look—you could save $200,000 in taxes.”
Of course you want to believe it.
I would too.
But remember:
The promoter doesn’t sign your tax return. You do.
Follow the Money
Before asking:
“How much will this save me in taxes?”
Ask:
“How does everyone involved make money?”
Who gets your $100,000?
Who earns the fees?
Is the person recommending the strategy getting paid?
Who provides the $400,000 loan?
And if you’re allowed to walk away from that $400,000...
who ultimately takes the loss?
If nobody can explain the economics in plain English, keep digging.
The Bottom Line
There are plenty of legitimate ways to reduce taxes.
And there are legitimate investments that generate large deductions.
But when someone tells you:
Put in $100,000.
Deduct $500,000.
Potentially save $200,000 in taxes.
Then walk away from $400,000 of debt.
Don’t let the complexity impress you.
Ask how it actually works.
Doctors, you work too hard for your money to invest $100,000 in something you don’t fully understand.
Do your due diligence.
And whenever possible, get a second opinion from a tax professional who isn’t being paid by the promoter.
If you’re a physician who’s been pitched something like this and want another set of eyes on it, feel free to reach out.
I’m happy to share what I’ve learned.